Many lenders finance used or refurbished equipment, though terms can be stricter since resale value and remaining useful life are harder to assess. An unsecured line of credit avoids this, since funds are not tied to the equipment purchased.
Yes. Businesses often finance part of the cost and pay the rest in cash. A line of credit suits this well, since it can be drawn in smaller amounts rather than requiring a loan for the full price.
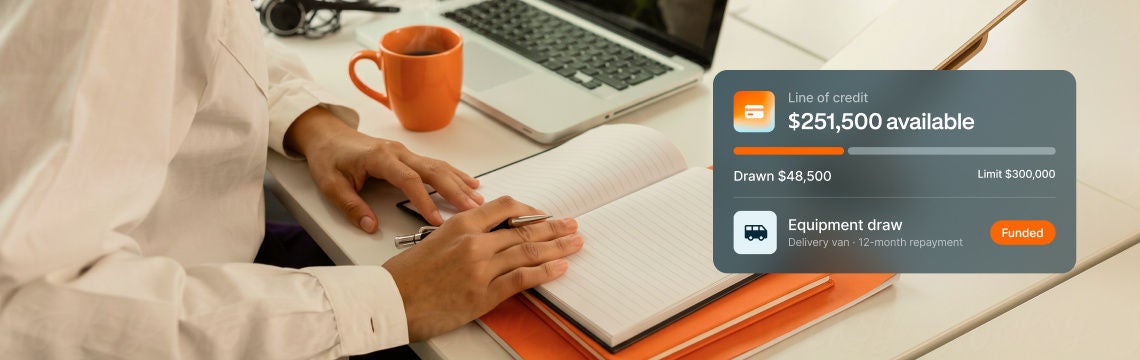
It depends on the lender. Some equipment loans require a minimum purchase amount to justify underwriting, while a line of credit like Avalara Capital has no mandatory minimum draw.
No. Collateralized loans use the equipment to secure the debt, but unsecured options, including a business line of credit, do not tie repayment to any single asset. That trade-off can affect pricing, so weigh it against how the equipment will be used.